

9 – 13 November 2026 🗓️
Inflation figures surprise, a divided technology sector and growing pressure on interest rate expectations.
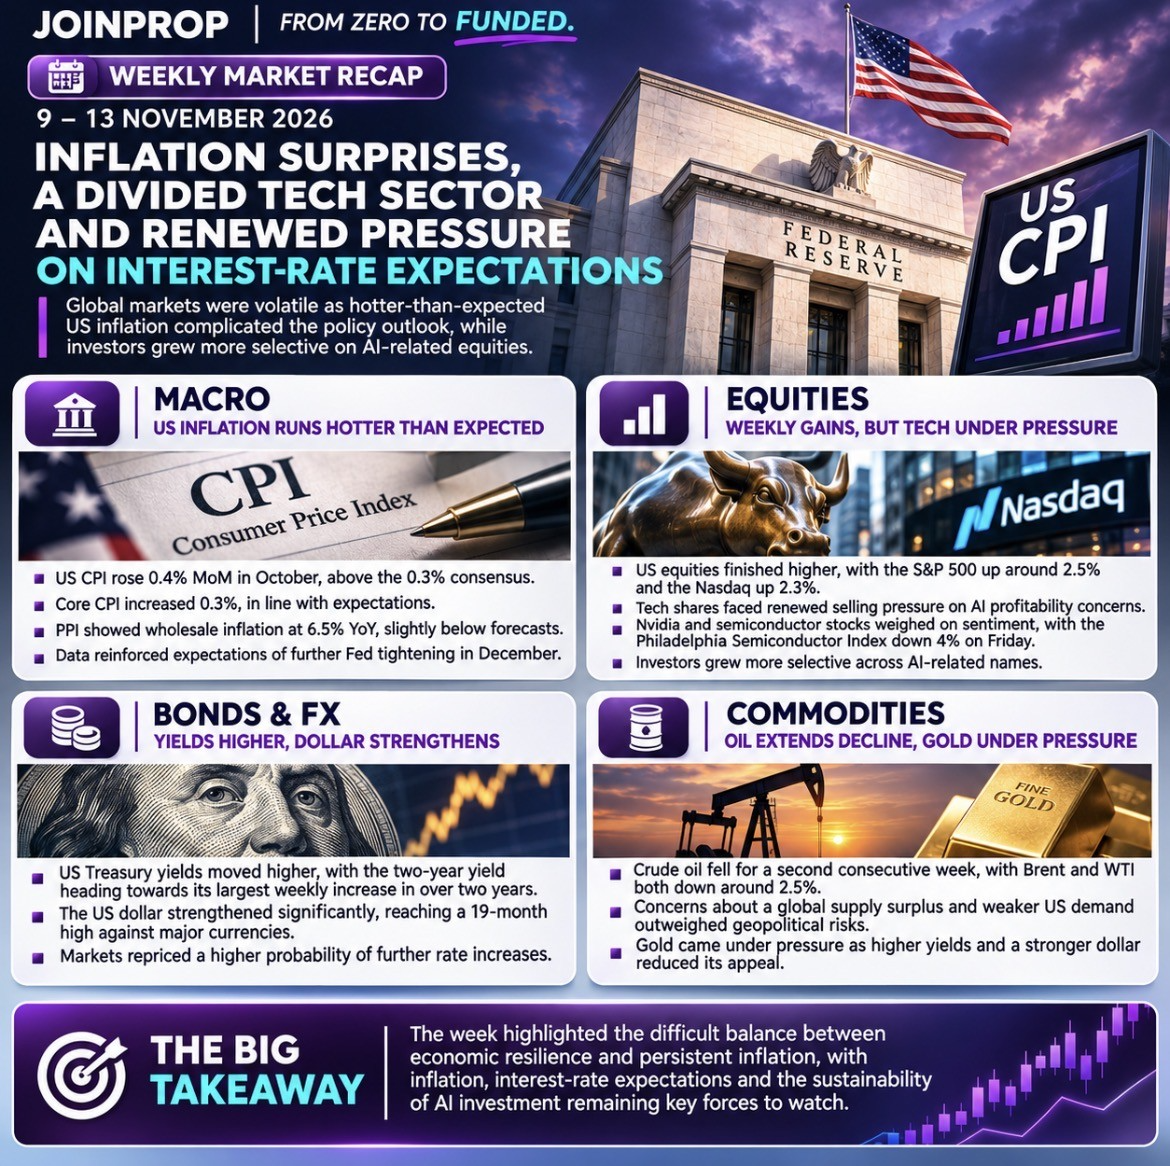
Global markets experienced a volatile week as hotter than expected US inflation complicated the outlook for monetary policy. Despite significant pressure on technology shares towards the end of the week, broader US equity indices managed to record their first weekly gains since early October.
🏛️ Macro
October’s US CPI report came in higher than expected. Headline inflation increased 0.4% month-on-month, against forecasts of 0.3%, while core CPI rose 0.3%. The BLS did not publish year-on-year inflation figures because comparable October 2025 data were unavailable following last year’s government shutdown. Friday’s producer-price report showed annual wholesale inflation at 6.5%, slightly below expectations, but price pressures remained elevated. The data strengthened expectations of further Federal Reserve tightening in December.
📈 Equities
US equities finished the week higher despite a difficult final session. The S&P 500 gained approximately 2.5%, while the Nasdaq advanced 2.3% after last week’s selloffs. However, technology shares faced renewed selling pressure as concerns surrounding AI profitability and developments involving Nvidia weighed on semiconductor stocks. Investors increasingly distinguished between companies benefiting from AI investment and those facing questions over the returns of that spending.
💵 Bonds & FX
Bond markets reacted to the changing inflation outlook. US Treasury yields moved higher, with the two-year yield heading towards its largest weekly increase in more than two years. The US dollar strengthened significantly, reaching a 19-month high against major currencies as investors reassessed the likelihood of further rate increases.
🛢️ Commodities
Crude oil extended its decline for a second consecutive week, with Brent and WTI both losing approximately 2.5%. Growing concerns about a global supply surplus and weaker US demand outweighed geopolitical risks in the Middle East. Gold also came under pressure following the inflation report, as higher yields and a stronger dollar reduced its demand.
🗺️ The bigger picture
This week highlighted the difficult balance between economic resilience and persistent inflation. Strong employment conditions and elevated price pressures are giving the Federal Reserve less room to ease monetary policy, while investors are becoming increasingly selective towards AI-related equities, questioning the effective sustainability of the elevated spending of the markets.
🟣 JoinProp – from zero to funded.
Enjoyed this article? Add JoinProp as a preferred source on Google.


