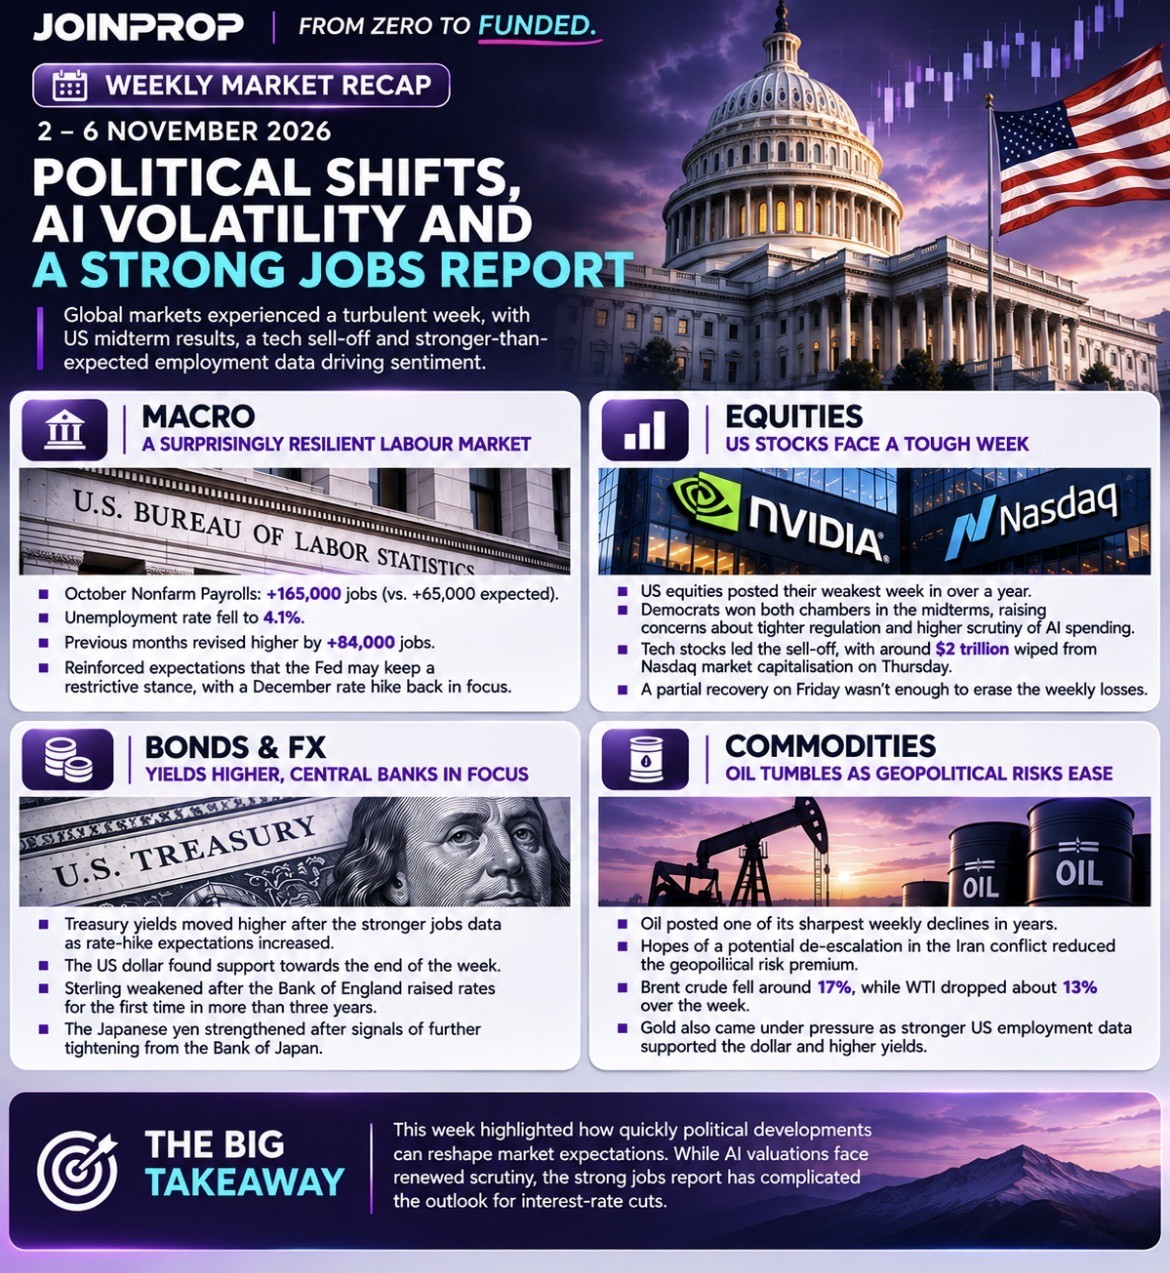
2 – 6 November 2026 🗓️
Political shifts, AI sell-off and a surprisingly strong US labour market.
Markets experienced a very turbulent week as the US midterm elections reshaped political expectations, triggering sharp movements across technology and energy markets. Friday’s employment report added another twist, showing that the US economy remains more resilient than anticipated.
📊 Equities
US equities endured their weakest week in over a year. The Democrats’ victory in both chambers of Congress raised concerns about tighter regulation and increased scrutiny of AI infrastructure investment. Technology stocks suffered a severe sell-off on Thursday, wiping approximately $2 trillion from Nasdaq market capitalisation. Friday brought a partial recovery, but the S&P 500 still lost 2.7% for the week, while the Nasdaq fell 3.4%.
🏛️ Macro
The October NFP report delivered a significant upside surprise. The US economy added 165,000 jobs, well above the 65,000 consensus, while unemployment declined to 4.1%. Previous months were also revised upwards by a combined 84,000 jobs. The figures reinforced expectations that the Federal Reserve may maintain a restrictive stance, with markets increasingly pricing in a December rate hike once again.
💵 Bonds & FX
Treasury yields moved higher following Friday’s employment surprise as investors reassessed the outlook for monetary policy.
The US dollar remained relatively steady during the week before finding support from the stronger jobs data. Sterling faced pressure after the Bank of England raised interest rates for the first time in more than three years, while the Japanese yen strengthened following signals of further potential tightening by the Bank of Japan.
🛢️ Commodities
Oil experienced one of its sharpest weekly declines in years. Hopes of a potential de-escalation in the Iran conflict following the US election results reduced the geopolitical risk premium, sending Brent crude towards a 17% weekly decline and WTI towards 13%. Gold also came under pressure as stronger US employment data supported the dollar and Treasury yields.
💡 The big takeaway
This week highlighted how quickly political developments can reshape market expectations. AI valuations, geopolitical risk and monetary policy remain deeply interconnected. While the technology sector faces renewed scrutiny over its investment returns, the strong employment report has complicated the outlook for interest-rate cuts.
As November progresses, investors will be watching whether economic resilience can withstand tighter financial conditions.
Enjoyed this article? Add JoinProp as a preferred source on Google.