
One Prop Trader a Day – Muhammad Osama Khan: A Failed Challenge Became Information


One Prop Trader a Day – Episode 141
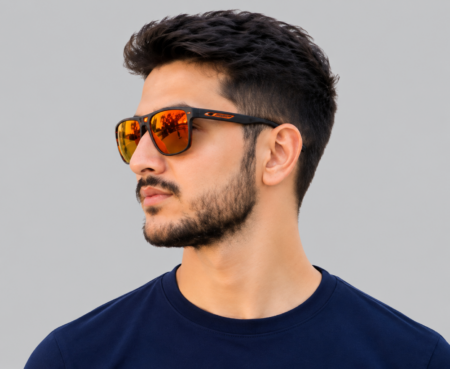
Muhammad Osama Khan
Muhammad Osama Khan is a 29-year-old trader from Karachi, Pakistan, who has been trading since 2019. He moved from technical and fundamental analysis to price action, Smart Money Concepts, VSA and ICT concepts, and now focuses on liquidity, time, market structure and execution. Here is his story, in his own words.
What do you do when years of losses teach you that knowing a lot about markets is not the same as having an edge? Muhammad Osama Khan, a 29-year-old trader from Karachi, Pakistan, has traded since 2019, blew multiple funded accounts and real accounts along the way, and became profitable in 2025. In this interview, he explains why he stopped treating trading as a collection of setups, how he works with liquidity, time and market structure, why he now waits for confirmation instead of anticipating, and what he would do in the first seven days with a 1 million dollar funded account.
Intro & Origin
My name is Muhammad Osama Khan. I am 29 years old and I am from Karachi, Pakistan. I started my trading journey in 2019, and what began as an interest in financial markets gradually became a long and demanding process of studying price behaviour, liquidity, execution and market structure. Over the years I have traded and studied financial markets with a particular focus on how price behaves around liquidity, time and important market levels. Today, my approach is much more systematic than it was when I started. I am less interested in simply asking whether a market is “bullish” or “bearish” and much more interested in understanding what is happening beneath the visible price movement: where liquidity may be resting, when it is likely to be targeted, and how price reacts after that liquidity is interacted with.
My journey into funded trading came after years of trial, error and repeated attempts to understand what actually gives a trader an edge. I would not describe the transition as one magical day when everything changed. The real change happened when I stopped treating trading as a collection of setups and started treating it as a problem of market behaviour, execution and risk. By 2025, the years of screen time and practical experience had changed the way I viewed losses, entries and probability. I was able to recover the losses accumulated during my learning years and, Alhamdulillah, reach profitability. Becoming funded was important, but the bigger achievement for me was developing a process I could trust and repeat.
For me, the strongest proof was not a particular luxury purchase. It was the moment trading stopped feeling like a constant fight for survival and started producing consistent results from a controlled process. After years of losses, being able to recover what I had lost and then operate profitably was more meaningful than buying something expensive. It represented something deeper: the possibility that the years of study, mistakes and discipline had finally turned into a repeatable skill.
The Grind
There were many failures. I went through a long period of losing streaks and blew multiple funded challenges/accounts as well as real accounts. I do not remember those failures as isolated events; together they became the price of my education. What kept me coming back was the belief that there had to be a deeper structure behind the movement I was seeing. Every time a method failed, I tried to understand why rather than simply replacing it with another indicator. That curiosity eventually took me from traditional technical and fundamental analysis to price action, Smart Money Concepts, VSA, ICT concepts and finally a much stronger focus on algorithms, liquidity, timing and execution.
The most expensive lesson was learning that knowing a lot about markets does not automatically mean you have an edge. I paid for that lesson through multiple blown funded accounts and losses in real accounts. Because I have not kept a single verified total in the information supplied for this interview, I would rather not invent a dollar figure. The real cost was both financial and psychological: I learned that an entry can look perfect and still be wrong, that a good idea can be badly timed, and that risk management has to survive periods when the market does not behave as expected.
Absolutely. Repeated losses can change the way you think. After enough losing trades, it is easy to become impatient, increase size, revenge trade, or start believing that the next position must recover the previous one. I experienced the pressure that comes with that cycle. Today I try to separate analysis from emotion. I focus on whether my conditions are present rather than whether I need to make money that day. I also accept that a valid setup can lose. The goal is not to avoid every loss; it is to make sure one loss does not change the behaviour of the next trade.
How You Trade Now
I have experience with funded trading and have gone through the difficult side of prop challenges, including failed accounts. For the published interview, I would prefer to name only firms whose names and trading history I can personally verify. What I look for in a prop firm is straightforward: transparent rules, clear drawdown calculations, reliable execution, sensible restrictions, predictable payout procedures and rules that do not encourage traders to take unnecessary risk. A good firm should make the rules understandable before the trader pays for a challenge.
My style has evolved considerably since 2019. I began with technical and fundamental analysis, then studied price action, Smart Money Concepts, VSA and ICT-style concepts. Eventually I became more interested in the idea that price movement is not simply a reaction to textbook supply and demand. My current framework focuses on liquidity, time, market structure, execution and the relationship between higher-timeframe context and lower-timeframe entries. I look for where liquidity may be pending, when price is likely to interact with it, and how the lower timeframe confirms or rejects the expected move. Rather than forcing trades throughout the day, I prefer selective entries where several conditions align.
My day begins before I think about an entry. I first establish the broader context: what the higher timeframes are doing, which major highs and lows are important, where obvious liquidity may be located, and what sessions or scheduled events could change volatility. Then I move down into the execution timeframe and wait. This waiting is important because my job is not to make the market move; it is to observe whether the market reaches the area I am interested in and then provides the behaviour I need. If the conditions do not align, I stay out. When a trade is taken, the priority becomes risk control and execution rather than continuously changing the thesis.
My most recent losing trades are useful because they remind me that even a strong model is not a guarantee. The type of mistake I am most conscious of today is entering too early, seeing the broader liquidity idea correctly but trying to anticipate the exact reaction before the market has confirmed it. In the past I would sometimes interpret a partial reaction as confirmation. Now I would rather miss a move than pay repeatedly for anticipation. The adjustment is simple: wait for the microstructure and timing conditions that define the entry, keep risk fixed, and accept that not every liquidity target produces the expected reversal or continuation.
My biggest milestone so far is not a single payout number; it is reaching the point where I recovered the losses from my earlier years and became profitable. In 2025, the experience I had accumulated finally started to translate into results. For me, that was a much bigger milestone than one unusually large winning trade, because it demonstrated that I could move from surviving the market to approaching it with a repeatable process.
Life & Reflection
Trading is difficult to explain to someone who has never spent years watching a market. From the outside, it can look like clicking a buy or sell button. From the inside, it involves research, probability, risk, waiting, execution and a lot of uncertainty. Over time, I think the people around me have understood that this is not something I discovered overnight. They have seen the years of study, the failures and the persistence. My results matter, but so does the discipline behind them.
I do not think the difference is that I am naturally more talented. The difference is that I was obsessed with understanding the reason behind the failure. If a strategy failed, I wanted to know whether the problem was the model, the timing, the execution, the risk or my own psychology. I kept refining the question. That mindset eventually changed my relationship with losses. A failed challenge became information instead of simply becoming a reason to quit. Persistence alone is not enough, but persistence combined with honest review can turn failure into experience.
I would not try to prove that I deserved a 1 million dollar account by making a 1 million dollar decision. The first seven days would be about protecting the account. I would study the firm’s exact drawdown rules, daily limits, payout conditions and execution environment, then establish a conservative risk framework. I would trade the smallest sensible size while observing how the account behaves under the firm’s rules. My objective would be to build a long-term process, not to maximise the first week’s return. A large account increases opportunity, but it also increases the cost of careless risk.
The Market Behind the Screen: Interbank FX, Liquidity & Algorithms
Important distinction: There is no single secret “interbank algorithm” that controls the foreign-exchange market. The institutional FX market is decentralized and fragmented. Banks, non-bank liquidity providers, funds, corporations, electronic trading firms and other participants use many different pricing, hedging, market-making and execution algorithms. What a trader sees as a price move is the result of interacting orders, liquidity, information, risk management and execution across venues, not one universal program.
The institutional FX structure
Spot FX and most FX derivatives trade over the counter rather than on one central exchange. Dealers intermediate between customers and liquidity providers, while electronic venues provide different ways to request quotes, match orders and access liquidity. Modern FX is highly fragmented: trading can occur through anonymous central limit order books, disclosed or quoted platforms, single-dealer venues, voice execution and other channels. The BIS describes this fragmentation and the increasing role of electronic and algorithmic execution in the modern FX market.
What “interbank” actually means
Historically, inter-dealer FX trading was a more distinct layer of the market. Today, that separation is less clear. Banks remain major liquidity providers, but non-bank electronic market-makers and principal trading firms also play important roles. Prime brokerage and electronic connectivity allow a broader set of participants to interact with wholesale liquidity. The result is better described as a network of liquidity pools and counterparties than as a single central interbank order book.
Where algorithms enter the process
Institutional algorithms perform different jobs. Execution algorithms may break a large order into smaller pieces, choose among liquidity venues, respond to changing spreads and market conditions, and attempt to reduce market impact. Market-making algorithms continuously update quotes and manage inventory and adverse-selection risk. Other algorithms may hedge exposures, detect relative-value opportunities, or manage order routing. BIS research notes that FX execution algorithms have evolved from simple mechanical slicing toward more adaptive methods that respond to real-time market conditions.
Liquidity: a more precise way to think about it
For a discretionary trader, “liquidity” is often used to describe obvious highs, lows or areas where stop orders may accumulate. At the institutional level, liquidity is broader: it includes the availability of counterparties willing to transact, the depth and quality of quotes, the ability to execute without excessive market impact, and the conditions across multiple venues. Some customer flow is also internalised by dealers, meaning trades can be matched within a dealer’s own liquidity pool rather than appearing transparently on an external venue. This is one reason why the visible chart cannot reveal every order in the market.
Why price can move quickly through a level
A level on a chart does not automatically cause a reversal. If aggressive orders consume available liquidity, quotes can be cancelled or repriced, or new information changes the balance of demand and supply, price can move rapidly. Automated execution can contribute to speed because algorithms can react and route orders much faster than a human. BIS research also notes that algorithmic execution can improve matching and price discovery while creating new risks, including changes in liquidity dynamics and possible self-reinforcing price moves.
Time matters, but not as a magical code
The idea that liquidity is connected to time has a useful practical interpretation. Institutional activity is not uniformly distributed through the day. Session openings, benchmark/fixing periods, economic releases, option-related activity, portfolio rebalancing and changes in participation can alter liquidity and volatility. A trader can therefore study when certain types of activity are more likely. But this should not be described as proof that an algorithm must attack a particular high or low at a predetermined minute. Timing is a probabilistic context, not a guaranteed script.
A practical model for the trader
My own evolution can be expressed as a sequence: Context → Liquidity → Time → Reaction → Micro confirmation → Risk → Execution → Review. First define the higher-timeframe environment. Then identify meaningful liquidity and the conditions that could attract price toward it. Next consider the time window and expected participation. If price reaches the area, wait for a reaction rather than assuming it. Use the lower timeframe to define an entry only when the required behaviour appears. Keep risk predetermined, execute without emotional escalation, and record the result for later review.
What this framework does NOT claim
It does not claim that retail traders can see the exact orders of banks, that every stop hunt is intentional manipulation, or that there is one hidden algorithm controlling the chart. It also does not claim that Smart Money Concepts, ICT, VSA, supply/demand or any other framework can predict every move. The useful part of these concepts is the discipline of thinking about market structure, order interaction, liquidity and timing. The market remains uncertain, and risk management remains essential.
Why my view changed after years of losses
When I started in 2019, I was looking for a method that would tell me exactly where to buy and sell. I moved through technical and fundamental analysis, price action, Smart Money Concepts, VSA and ICT concepts. The deeper lesson was that a setup is not the same thing as an edge. I became more interested in the mechanism behind the movement: who might need liquidity, how orders can be executed across fragmented venues, why timing changes behaviour, and how a lower-timeframe entry can be aligned with a broader hypothesis. That shift in thinking is what I consider the foundation of my current approach.
Final perspective
The biggest lesson from my journey is that trading is not about finding a perfect indicator or discovering a secret algorithm. It is about developing a coherent model, testing it, controlling risk and staying intellectually honest when the market proves you wrong. I spent years paying for that lesson. Today, Alhamdulillah, I am profitable, but I still treat the market with respect. The objective is not to predict everything. The objective is to recognise the situations where my process has an advantage and to manage the situations where it does not.
My take on the firms
My experience with prop trading taught me that the quality of a firm is not just about the advertised challenge. The rules, drawdown model, execution environment and payout process all matter. A trader should understand the rules before purchasing an account and should choose a firm whose structure supports disciplined risk management rather than encouraging excessive risk-taking.
Verified funded – the receipts
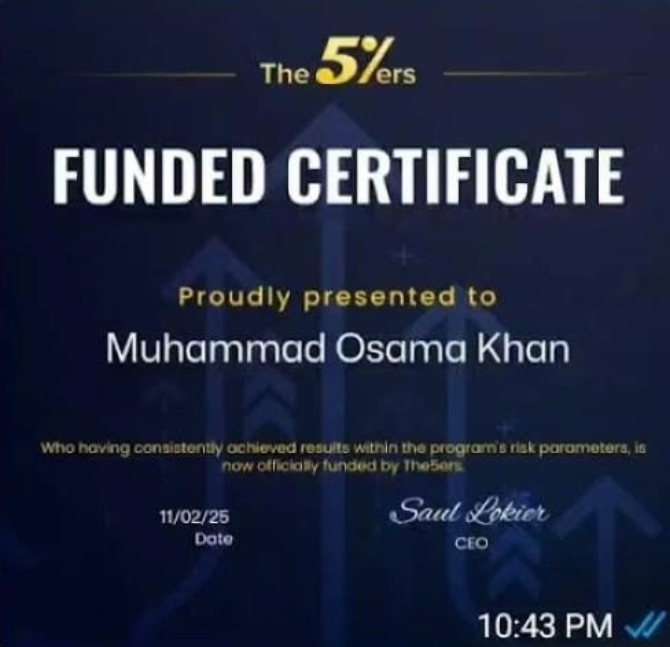
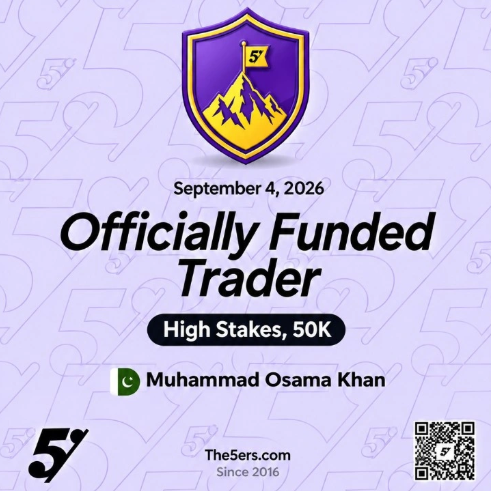
About the writer – Muhammad Osama Khan
Muhammad Osama Khan is a 29-year-old trader from Karachi, Pakistan, who has been trading since 2019. He moved from technical and fundamental analysis to price action, Smart Money Concepts, VSA and ICT concepts, and now focuses on liquidity, time, market structure and execution.
Enjoyed this article? Add JoinProp as a preferred source on Google.


